
RATA
Fair Servicing: What Examiners Test in Servicing Data, and How to Test It First
Fair lending examination does not stop at the credit decision. A servicer that grants a forbearance to one borrower and denies it to a similarly situated borrower on a prohibited basis has a fair lending problem, even though no application was declined and nothing about it will ever appear on a HMDA loan application register. The CFPB instructs its examiners to test for precisely this. The data they need to do it does not live in your LAR. This article covers what those servicing decisions are, why origination-side testing cannot see them, and how the statistical methodology used on application data transfers to servicing data. It is also specific about where that methodology stops transferring cleanly, because that is the part most treatments of this topic skip. What fair servicing…
What Actually Counts as a Small Business Loan Under Section 1071
A financial institution is a covered institution under Section 1071 if it originated at least 1,000 covered credit transactions to small businesses in each of the last two calendar years, where a small business is one with gross annual revenue of $1 million or less. Both numbers changed on May 1, 2026, when the CFPB published a reconsideration final rule that raised the origination threshold from 100 and lowered the revenue ceiling from $5 million. If your institution is testing scope against the older figures, the test is wrong, not just outdated. The rule's definition of a small business, and where the revenue threshold sits Section 1071 of the Dodd-Frank Act only counts credit extended to a "small business," and the definition is entirely about gross annual revenue: $1 million or…
The ComplyBI Era Has Arrived
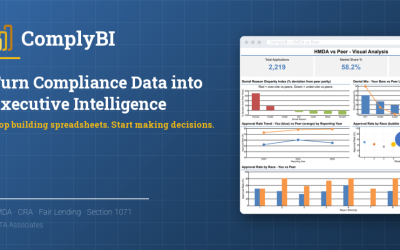
This past weekend marked an exciting milestone for RATA and our clients. With the latest RATA Hosted Services (RHS) release, the first wave of ComplyBI functionality is now available to all RHS clients. This isn't just another software update. It marks the beginning of a new era in compliance analytics. For decades, compliance professionals have relied on static reports, spreadsheets, and manual analysis to understand their data. ComplyBI changes that by transforming compliance information into dynamic, interactive intelligence that helps you identify trends, uncover risk, and gain deeper insight into your institution's compliance performance. Unlike generic business intelligence tools, ComplyBI is RATA's proprietary analytics platform, designed specifically for regulatory compliance.…
Comply 25.1 Update Now Available
Since the release of Comply 25.0 in late October, our development team has continued enhancing the Comply Suite with new features, performance improvements, and stability updates. We are pleased to announce that Comply 25.1 is now available. Highlights of this Release Introducing ComplyBI – A powerful new business intelligence and analytics component of the Comply Suite. ComplyBI provides interactive dashboards, visual analytics, and executive reporting for HMDA, CRA, and Small Business Lending (SBL) data, helping you gain deeper insight into your compliance information than ever before.Enhanced Mapping Technology – Comply has been upgraded to the latest MapSuite technology, delivering improved mapping performance, greater stability, and integration with the Open Maps base…
2025 HMDA Peer Data Official Release is Available
The CFPB has released the official 2025 national HMDA peer data as of June 23, 2026. We downloaded and converted the data and, as in the past, made sure to match all Institution IDs with the preliminary data that was released on April 3. By ensuring that the Institution IDs align with one another between these sets of data, all Peer Institution Groups created with the preliminary data will continue to work the same as before. It is the CFPB's intent to potentially release updates to the 2025 HMDA data based upon re-submissions, late submissions etc., and we intend to review the extent of any changes periodically to see if updates are warranted. Installation of the Peer data is accomplished as follows: On-premise (client site) Comply installations Download the data for use in…
- 2026 HMDA Data: Your Filing Checklist for the March 1, 2027 Deadline
- How to Evaluate Fair Lending and CRA Software: What to Test Before You Sign
- How to Evaluate Fair Lending and CRA Software: What to Test Before You Sign
- HMDA Plus: What It Actually Changed in the LAR Workflow
- What a Fair Lending Exam Actually Asks For
- 2026 HMDA Data: Your Filing Checklist for the March 1, 2027 Deadline
- HMDA Plus: What It Actually Changed in the LAR Workflow
- How to Fix the 10 Most Common HMDA Edit Check Errors
- How to Evaluate Fair Lending and CRA Software: What to Test Before You Sign
- What a Fair Lending Exam Actually Asks For
- Fair Servicing: What Examiners Test in Servicing Data, and How to Test It First
- What Actually Counts as a Small Business Loan Under Section 1071
- Section 1071 in 2026: What Lenders Need to Know About Small Business Lending Data
- How to Evaluate Fair Lending and CRA Software: What to Test Before You Sign
- Special Report: Geocoding - Achieving the Highest Accuracy

